
Florida’s current approach to insurance is forcing those who can least afford it to bear the cost of the climate crisis. But different approaches are available.
Articles on Home insurance
Displaying all articles
A nationwide scheme known as Flood Re is only a temporary fix.
Climate change is undermining insurance markets, especially for the households that need coverage most.
The California approach promises to keep home insurance prices stable, ensure coverage in high-risk areas, and make homes safer as climate change worsens.
Central bankers agree that climate change poses a threat to the financial system. An insurance crisis is exactly the kind of problem that could spread.
Low-income households are attracted to more affordable housing in areas at higher risk of floods and other extreme events. But many then find they cannot afford soaring insurance premiums.
Insurers are raising rates quickly, and it’s not just in California and Florida. They’re often shrinking coverage at the same time.
Australian properties are becoming uninsurable as unseasonal extreme weather inflicts major damage to housing, business and infrastructure.
Insurance companies will need to be innovative and explore new policy options as they manage the growing risk to homes from climate change and natural disasters.
With average insurance premiums up 28% in the past year, there’s growing pressure on the insurance industry to rethink its opposition to a government-owned and run disaster reinsurance pool.
The insurance industry should be involved in planning for future disasters and resilience, before some parts of New Zealand become uninsurable – leaving mortgage holders and banks exposed.
Natural disasters are driving up insurance costs. The Australian government’s plan to drive them down won’t help much.
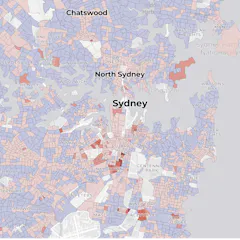
Even if you’re well covered, your area may struggle long after a disaster if most locals don’t have enough home and/or contents insurance. Search our map by postcode or suburb name to check your area.
Private companies rate all kinds of investments, from stocks to used cars. Now, they’re starting to analyze climate risks to local real estate – but how reliable are their findings?
The Morrison government’s reinsurance pool is the exact policy the Australian Competition and Consumer Commission recommended against.

Instead of telling people to buy more of the right type of insurance, we should be asking how insurance can work better for people.
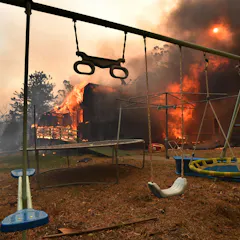
One lesson from Australia’s past bushfire disasters is that too many homes are underinsured. But it’s a lesson we’ve failed to learn.
Top contributors
-

Associate Professor of Human Geography, University of Tasmania
-
Lecturer and Research Fellow, School of Geography, Planning, and Spatial Sciences. Coordinator, Education for Sustainability Tasmania, University of Tasmania
-
Principal Investigator FiRES Project (SNSF Consolidator Grant), ETH Zürich, Switzerland // Honorary Associate Professor, University of Wollongong, Australia.
-
Professor in Strategic Management, The University of Queensland
-
Lecturer, Monash University
-
Postdoctoral Research Fellow, The University of Queensland
-
Senior Lecturer in Financial Economics, Loughborough University
-
Senior Lecturer in Finance and Insurance, Te Kunenga ki Pūrehuroa – Massey University
-
Provost Professor of Economics and Spatial Sciences, USC Dornsife College of Letters, Arts and Sciences; Institute for Humane Studies
-
Lecturer in Law, Auckland University of Technology
-
Professor of Water Engineering, Loughborough University
-
PhD Candidate in Geography and Demography, Penn State
-
Postdoctoral Research Fellow, Strategic Management, The University of Queensland
-
Holcim (US) Professor of Sustainable Enterprise, Ross School of Business, School for Environment & Sustainability, University of Michigan
-
PhD Student, Bayreuth University