
The sector risks repeating the mistakes which led to huge tax-payer funded bail outs.
Articles on UK banking
Displaying 1 - 20 of 23 articles
More diversity in the banking sector can help with stability, but Revolut’s two-year wait for a UK banking licence indicates regulatory caution.
Research shows banks – especially private banks – have always been concerned about their customers’ social status and respectability.
Banks in the UK have to conduct extra checks on people more at risk of blackmail – and an easier option is sometimes just to say no to giving them and account.
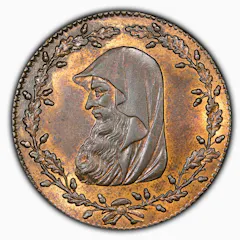
A Welsh mining company was the first to issue tokens to workers as an alternative form of payment.
Women have had to forge their own identity at work but still face issues based on their appearance.

My research suggests City firms’ efforts to deliver more equal representation at the top have not worked because they were never meant to.
New green finance measures aside, UK chancellor Jeremy Hunt’s Edinburgh reforms look like history repeating itself.
Research suggests that big bonuses encourage big risks.
Government moves to encourage longer and larger home loans won’t address housing affordability in the UK
NatWest and HSBC are restricting customers in their crypto-dealings.
UK banks have been given six months to prepare for rates going below zero.
Contactless payments may be convenient – but they also make it easier to overspend.
Trust has been broken, and will not be easily fixed.

Challenger banks are on the rise but they need to prove themselves to be trustworthy to survive – and profit.

With a bit of government backing, alternative finance can give us control over our money and help kickstart the ‘real economy’.
A common cry from regulators is that customers must shop around for the best deal – but households rarely look for a better banking deal.
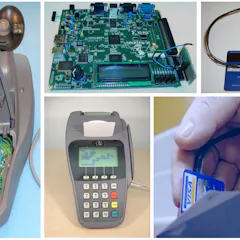
A loophole in a change to contactless card to prevent fraud had this security sleuth on the case.
The Commonwealth Bank’s half year results suggest Australian banks are doing well despite the turbulence affecting banks internationally, however they may not be totally immune.
The Co-op Bank faces an uphill struggle to win back credibility with the regulator, with investors, and, crucially, with customers.
Top contributors
-

Head of Department of Economics, Finance & Accounting, Brunel University of London
-
Professor in Business History, Henley Business School, University of Reading
-
Reader of Commercial Law, Queen's University Belfast
-
Royal Society University Research Fellow, UCL
-
Professor of Climate Justice, Queen Mary University of London
-
Associate professor in Political Economy, University of Birmingham
-
Associate Professor of Sociology, University of Leeds
-
Director, Newcastle University Business School, Newcastle University
-
PhD Researcher, Warwick Business School, University of Warwick
-
Chair in Finance, University of Aberdeen
-
Professor and Chair in Financial Technology (FinTech) & Information Systems, University of Manchester
-
Senior Lecturer in Business and Commercial Law, Lancaster University
-
Lecturer in Finance, Bangor University
-
Associate Professor Marketing, Bournemouth University
-
Professor, Finance, The University of Western Australia