
High rates of outright home ownership combined with tax-free super insulate older Australians from mortgage rate fluctuations.
Articles on Retirement incomes
Displaying 1 - 20 of 24 articles
A lot of Australians are hoping there might be an interest rate cut at the next Reserve Bank board meeting but they shouldn’t hold their breath.
If you are aged 70 with a million dollar home you could get up to $308,000 per year from a little-known scheme with risks.

The coronavirus stock market crash is more jumpy, and harder to rein in, in part because of the role of retirees.
The government’s retirement incomes review should concentrate on boosting rent assistance and Newstart and fixing the pension assets test. These would achieve more than boosting super.
More older Australians are carrying housing debt later in life, or not owning homes at all, but lack suitable alternatives to the family home. The result is lower incomes in retirement.
No single super contribution rate suits everyone, and there’s only a clear case for an increase if there’s no age pension.
Retires who don’t own their homes do awfully out of the pension. Here’s a way to rebalance it.
The inquiry will find we force workers to sacrifice income, pay tens of billions in super tax concessions, and still pay out one in every ten dollars of government earnings on pensions.
One of the questions is how much we need in retirement. Another is whether we need 12% compulsory super to get there.
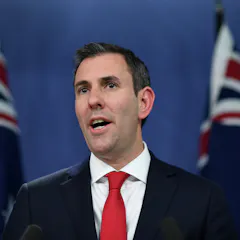
Jim Chalmers on the need to change economic course
The Conversation, CC BY35.9 MB (download)
In this podcast, Shadow Treasurer Jim Chalmers argues the government can have both a more stimulatory policy and a surplus going forward.
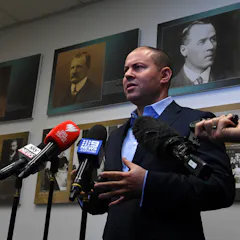
Politics with Michelle Grattan: Treasurer Josh Frydenberg on a slowing economy
This week's June quarter national accounts showed the weakest economic growth since the GFC, but Treasurer Josh Frydenberg remains optimistic.
People over 65 who still have a mortgage or are renting are projected to double in number by 2031. The trend is likely to hit government budgets and leave more retirees in poverty.
Making super voluntary for low earners, as proposed by a Liberal senator would leave more women vulnerable in old age.
There is a case for not proceeding with, or at least deferring, the legislated increase in employers’ compulsory super contributions, but it isn’t the one the Grattan Institute makes.
Whether you owned a home or not used to be straightforward. The boundaries are becoming permeable.
Often misunderstood, deeming rates are back broadly where they should be.
It’s a good idea to deem income, but of late we’ve doing it badly.
New calculations suggest middle earners will earn less over their lives if compulsory super is ramped up from 9.5% of salary to 12% as scheduled.
It is widely believed that compulsory super saves the government money on pensions. It does, but nowhere near enough to pay for the accompanying tax concessions. Lifting compulsory contributions will make things worse, for a century.
Top contributors
-

Visiting Fellow, Crawford School of Public Policy, Australian National University
-
John Curtin Distinguished Professor, Curtin University
-
Program Director, Housing and Economic Security, Grattan Institute
-
Emeritus Professor of Housing and Housing Studies, RMIT University
-
Professorial Fellow, University of Canberra
-
Adjunct Professor, Curtin Law School and Curtin Business School, Curtin University
-
Adjunct Associate Professor, University of Tasmania
-
Research fellow, Curtin University
-
Associate Professor in the UNSW Business School, UNSW
-
Associate Professor, College of Business and Economics, Australian National University
-
Industry Professor, University of Technology Sydney
-
Associate, Grattan Institute
-
Senior lecturer, Canberra School of Government, University of Canberra
-
Associate Professor, gender, ageing and care, University of Sydney
-
Senior Lecturer in Actuarial Studies, Australian National University