
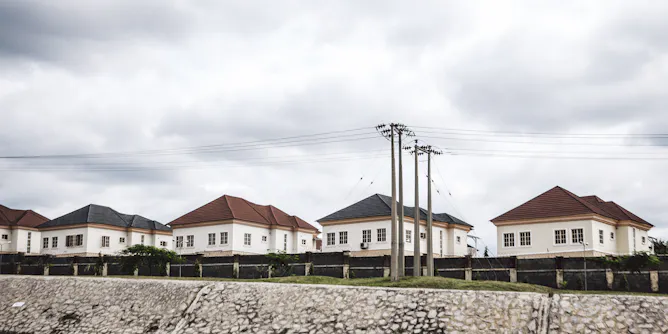
Nigeria’s housing policies have failed to meet the needs of its federal capital residents.
Articles on Mortgage rates
Displaying 1 - 20 of 38 articles

Investors’ inflation expectations, much more than the central bank, are among the factors that affect the cost of home loans.
There is a range of important reasons why home ownership remains elusive for many Australians. But there are solutions.

The cost-of-living crisis has been exacerbated by mortgage and rental stress. Housing affordability and availability are defining issues for the election and beyond.
The Conversation’s expert panel expects the Reserve Bank to cut interest rates two to three times over the next 18 months, with the first cut likely in March.
Living standards have fallen for the fifth successive quarter, the longest decline in 40 years.

Homeowners looking to remortgage and first-time buyers struggled to manage interest rate hikes in 2023. Here’s what to think about this year.
A lot of Australians are hoping there might be an interest rate cut at the next Reserve Bank board meeting but they shouldn’t hold their breath.
Australian financial markets are now pointing to a close to zero chance of further rate rises – with a fair chance of a rate cut next year. That’s thanks to the latest news from the US and UK.
Central banks balance different factors when raising rates – or not – including inflation and the labour market. But what other countries are doing also has an effect.
Complaints that our recommendations would weaken the Reserve Bank governor ignore the fact that outsiders already control the board. We just want them do it better.
The way banks calculate interest means that Australian borrowers who sign up to pay 5.95% per annum pay something closer to 6.11%.
We hear a lot about the negative impact of rate rises on mortgage repayments while little is made of the benefits of high interest rates.
Australian home borrowers are experiencing much, much more interest rate pain than borrowers in New Zealand, Canada, the UK or US – for one simple reason.
The good news includes a return to real wage growth and a restrained increase in unemployment. The bad news includes even higher home prices and a per-capita recession.
Interest rate hikes are the Bank of England’s main monetary policy weapon against inflation, but they aren’t working.
The Reserve Bank governor has only three months left in the job and he isn’t yet sure inflation is on the way down.
More than one million borrowers are set to come off ultra-low fixed mortgage rates this year and next, meaning the full effect of the ten rate rises to date is yet to be felt.
UK borrowers are expecting mortgage rates to fall again. Here’s why this looks unlikely in the current economic environment.
I graphed the average online rate for a $10,000 deposit against the Reserve Bank’s cash rate, going back to 2010. After seeing what that graph reveals, you’ll want to call your bank.
Top contributors
-

Visiting Fellow, Crawford School of Public Policy, Australian National University
-
Senior lecturer, Canberra School of Government, University of Canberra
-
Lecturer in Economics, Monash University
-
Head of Department of Economics, Finance & Accounting, Brunel University of London
-
Professor of Economics, University of Leeds
-
PhD Candidate, Sustainable Urbanisation, University of Lagos
-
Professor, Finance, UTS Business School, University of Technology Sydney
-
Program Director, Housing and Economic Security, Grattan Institute
-
Senior Lecturer in Economics, The Open University
-
Professor of Finance, University of Florida
-
Professor of Economics, Crawford School of Public Policy, Australian National University
-
Senior Lecturer, School of Accounting, Auditing and Taxation, UNSW
-
Associate Professor in Finance, University of Sydney
-
Associate Professor of Finance, Mississippi State University
-
Emeritus Professor of Finance, The University of Melbourne